
Can I claim R&D tax credits if I’m a loss making company?
If your company has been making a loss, it’s still worthwhile making a claim for R&D tax credits. Sometimes this is misunderstood with people thinking a company needs to be profitable to benefit. However, applying as a loss making company can provide significant and quick cash returns for your work.
How much cash can be claimed by loss-making companies?
A company can receive a payable tax credit, which is effectively a cash or cheque payment directly to them. This is worth up to 33p per £1 spent on qualifying R&D costs.
E.g. A qualifying cost of £100,000 on R&D activities can generate a cash payment of £33,350. The Company can still benefit - even if they have never made a profit or paid any corporation tax! However - there is a limit to this payout that might apply to some companies.
Is there a cap on the tax credit for loss-making companies?
When a company is taking a payable tax credit there is a cap that recently came into force that can limit the amount.
The cap is calculated as £20,000 plus 3 x the company's PAYE and NI contributions. Companies with small annual payroll amounts are more likely to be restricted in their tax credit claim.
How loss-making companies receive their R&D tax credit
If a business is loss-making, there are two options for receiving benefit from an R&D tax credit claim.
- They can surrender their trading losses, which arises as a result of their claim, for a cash repayment. This is the payable tax credit and leads to a benefit of up to 33% of a companies R&D spent.
- Or they can carry their trading losses forward. This allows them to reduce their corporation tax bill in future years when they make a profit. When the company has made enough profit to offset all of its trading losses - it will receive a benefit of up to 44% of its R&D spend.
A company can choose to use some of its claim (technically the losses arising from the claim) for taking a payable tax credit and can carry some losses forward.
For example - if they are affected by the payable tax credit cap - they can take the maximum allowable payable tax credit and carry forward their remaining losses to a future tax year. This will allow them to benefit from a payable tax credit now, and a reduction in corporation tax in the future.
How to choose between carrying losses forward and taking a payable tax credit
Let’s look at an example where a company has spent £100k on R&D and is deciding between surrendering their losses or carrying them forward:
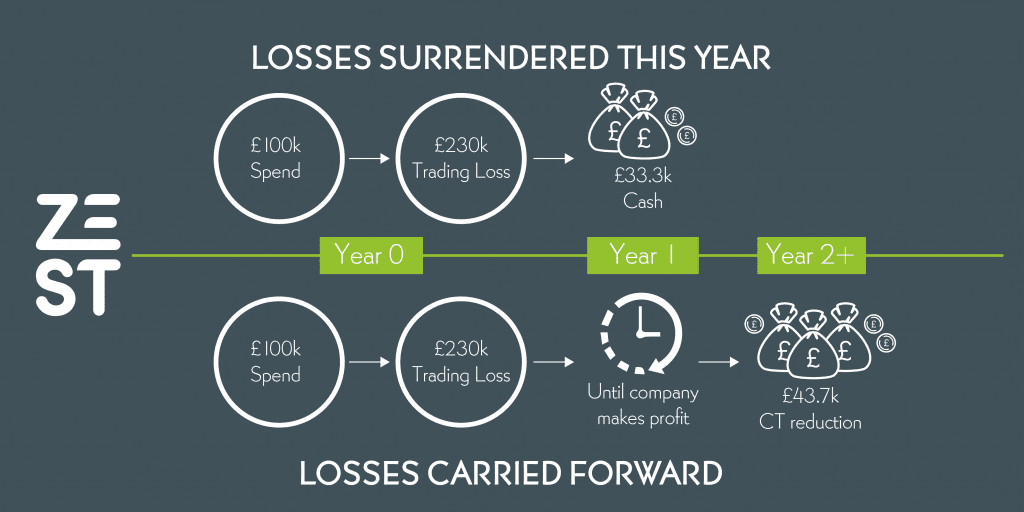
The company's trading losses have increased by £230k as a result of applying the R&D tax credit to their £100k investment in R&D. They can now choose between surrendering this £230k loss for a payable tax credit - or carrying it forward. To understand how these calculations work - check-out this blog.
The decision about how this company uses their R&D tax claim will depend on a few things:
- Is the company expecting to be profitable soon? If yes - they are more likely to benefit from carrying the losses forward. This is because they are more likely to have a corporation tax bill in the near future, which would be reduced by any losses they carry forward.
- Is the company already carrying forward trading losses? If yes - they will not benefit from carrying losses forward until all of their existing trading losses have been used up.
- Does the company need funding for growth plans? Receiving a £33k refund now might be more important than receiving the £44k tax reduction in the future.
These factors will be the same for all companies making this decision. The right answer will always depend on the context of the business. Professional and competent R&D advisors will help you make the right decision for your business, by guiding you through this decision.
Need help or have any questions?
When making an R&D claim, employing the services of a specialist advisor will ensure you get the best possible results. At Zest R&D we specialize in preparing and submitting R&D claims. Our priority is ensuring your R&D tax claim works for you. If you are considering making a claim for R&D tax relief or would like to discuss the status of an existing claim, please don’t hesitate to get in touch.
Other news stories

R&D Tax Credit Statistics 2026: Why SME Claims Are Falling (And What It Means for You)
HMRC’s R&D tax credit statistics 2026 show SME claims down 19% even as total relief rises — what’s behind the fall and what it means for your claim.

How Does the Patent Box Work? A Complete Guide for UK SMEs
How does the Patent Box work? A plain-English guide to the 10% Corporation Tax rate on patent profits — eligibility, the development condition, the R&D nexus, how to elect, and a worked example.

Autumn Budget 2026 and R&D Tax Relief: What to Watch on 28 October
The Chancellor will deliver the Autumn Budget 2026 on Wednesday 28 October. For any UK company running an R&D tax relief claim — or planning its first — it is worth knowing what is genuinely on the table before the red box opens, and what is simply noise. The short version: after three years of near-constant reform, the R&D regime is finally settling. Most of what matters for your next claim is already law. But a Budget always carries the risk of a technical tweak, and there are a few signals worth tracking. Where the R&D rules stand going into the Budget The big structural change is done. The merged RDEC scheme is now the default for accounting periods beginning on or after 1 April 2024, replacing the old separate SME and RDEC regimes. It gives a taxable expenditure credit of 20% of qualifying R&D costs — worth roughly 15% net once Corporation Tax at 25% is applied. Loss-making, R&D-intensive SMEs are the exception. If your qualifying R&D is at least 30% of total expenditure, you may instead claim under Enhanced R&D Intensive Support (ERIS), which offers a more generous deduction and a payable credit for surrenderable losses. None of […]
